CondoWonk: Research and Ideas You Won’t Find Anywhere Else.

CondoWonk is a California-based guide to condominium life, featuring human stories, original research and creative problem-solving. Grounded in a deep understanding of condominium theory and practice, CondoWonk questions conventional wisdom, seeks practical solutions and supports innovative policy approaches.

CondoWonk is for HOA presidents and board members, residents, managers, policymakers and anyone else who wants insight into the real issues facing condominiums.

*WONK (noun): A person who takes an enthusiastic or excessive interest in the specialized details of a particular subject or field.

Latest Articles

Browse by Topic

Property

Your building, and how you pay to keep it up

Most Recent

HOA Reserve Fund Tax: Why Your Association Pays a Higher Rate Than Apple

All Property articles →

People

The human side of boards, votes and neighbors

Most Recent

What The Camera Saw

All People articles →

Policy

Legislation, "Best Practices" and even better ideas

Most Recent

California Condo Legislative Report: Midnight Mayhem as a Major Bill Goes Missing

All Policy articles →

Latest Articles

CondoWonk is not just a website, it’s an information-sharing network of condominium boards, owners, managers and others, trying to make our communities run better. Share your questions, what worked and what didn’t. 

You Had Me At "Wonk"

"After spending two solid days and nights on the computer researching electric vehicle charging, and finding the rabbit hole getting bigger and bigger, I ran across your website. After an unsuccessful attempt at getting to sleep, I got up, and starting delving into more of my EV questions. It's 3:54 am, and when I found your articles and saw the meaning of the word "wonk" on your homepage, I was hooked! Your articles on EV chargers gave me an even bigger picture of what lays ahead for us in the EV world for condos. As President of our HOA's 12-unit condo building, please accept my heartfelt thank you for putting this site together!"
Kathleen H.
HOA Condo President
Doris Sussman Goldstein
Meet the Author

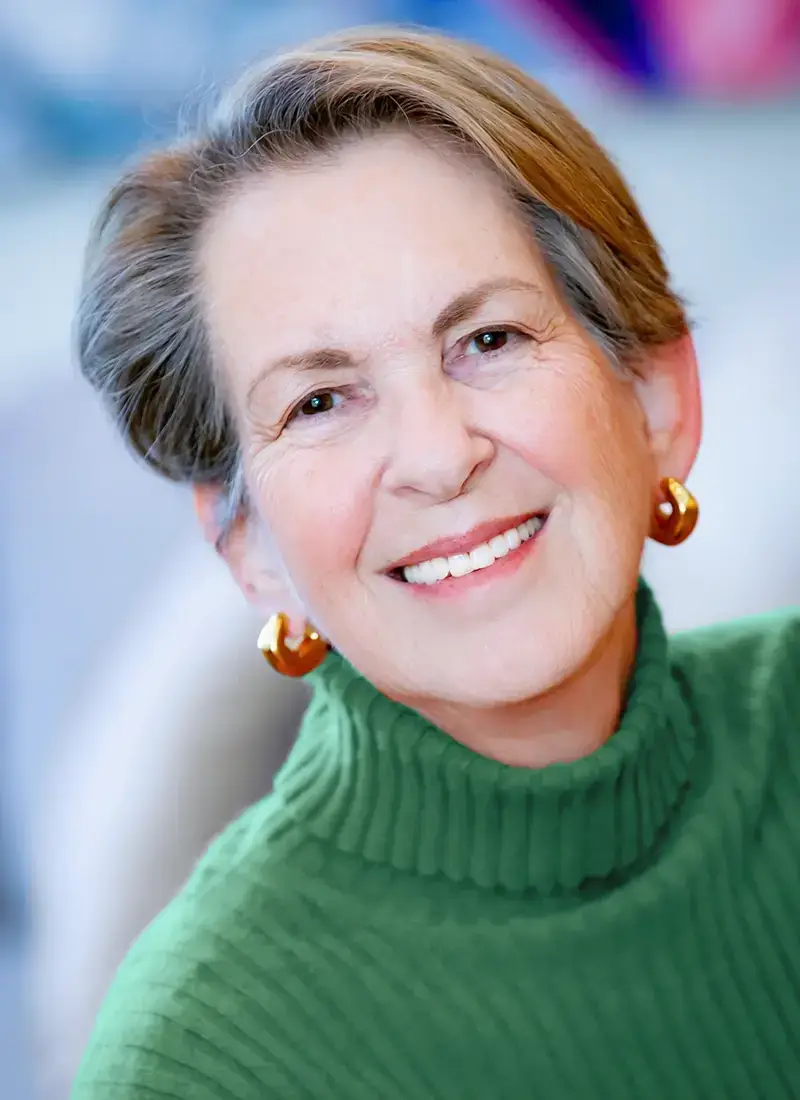
Doris Sussman Goldstein

Doris Sussman Goldstein is the writer and publisher of CondoWonk. She combines a deep understanding of condominium theory and practice with a journalism background and hands-on experience as president of her own building in Los Angeles.

Read Her Full Story

THE QUESTIONS WE HEAR MOST

Common Questions

The principle of condominium ownership is simple. A condominium subdivides ownership in a property into private space (units) and shared space (the common area) so that each unit owner can buy, sell and mortgage their unit.

Homeowners own their unit and can, with some restrictions, do what they want inside their unit. But they also own the rest of the building (common area), together with their neighbors, in undivided shares. That means they have a percentage interest in the building structure and everything else that can’t be separated from any other owner’s interest.

Everything that follows from that concept—legislation, recorded covenants, conditions and restrictions (CC&Rs), rules, budgets and assessments—is an attempt to allow random strangers to make decisions together concerning the property they share.

And that’s where things get complicated.

All condominium projects are common interest developments but not all common interest developments are condominiums.

Generally, a common interest development or common interest community is one that includes both private ownership of living space and shared use of common areas. In addition to condominiums, it includes planned communities with privately owned homes if they have a homeowners’ association.

The Davis-Stirling Act, as explained further below, applies to every Common Interest Development, which in Civil Code 4100 defines as including both condominiums and planned communities but also includes two less popular forms, a community apartment project (often known as “Tenancies in Common”) and a stock cooperative (commonly known as a “co-op”).

Particularly in a state like California, where housing prices are extremely high, a condominium may be the most affordable housing option, especially if you care more about interior space than having a yard. Condominiums may be in more walkable neighborhoods, closer to transit and local retail, than living in a single-family home. Some condominiums may give you amenities such as a pool or a gym. And you may like the security of having people around and not having to do a lot of maintenance.

On the negative side, condominium living comes with a certain loss of personal autonomy. Don’t move into a condominium if you are going to be annoyed by your neighbor’s noise, their cooking odors or other habits.

And the board will be calling the shots on how well the place is maintained, what projects to prioritize and how much you will be required to pay. In your own house, you can decide if it’s time to replace the roof or to let it go another year. In a condominium, the board makes that decision and collects the money from the owners to pay for it.

No matter how much research you do, there is no way of knowing exactly what you will end up paying.

You will know what the monthly assessments, commonly called HOA dues, are when you buy your unit. That does not, however, guarantee what dues will be in the future.

Some buildings keep dues artificially low by neglecting repairs, and then special assessing for everything when things fall apart. Or, worse, NOT special assessing and letting things continue to decay.

The amount of dues depends a great deal on the type of building, its age, its amenities and what’s included in dues. For instance, if the HOA is providing hot and cold running water, that could easily be $150 per unit that’s included in the HOA dues—but saves you money out of your own pocket.

Insurance is usually one of the biggest line items in any HOA’s budget. In today’s market, that number could suddenly double, or more, without warning.  

In short, buildings cost what they cost. Being proactive with maintenance saves money in the long run. And buying a house also comes with all kinds of expensive repair surprises.

California Civil Code 4745 says HOAs have to allow homeowners to install EV chargers with only “reasonable restrictions.” In real life, it gets messy, and expensive. Condowonk has extensive information about how to make it work.

The HOA’s master policy insures against various risks to the building, such as fire, or a sudden event leading to water damage. It has deductibles—often large ones—and, as discussed below, it probably doesn’t cover the inside of the unit.

An HO-6 policy is a policy that an owner can purchase for themselves to cover some of the risks that the master policy doesn’t. (Some HOAs and some lenders require unit owners to carry HO-6 coverage.)

To get proper coverage, you need to know where your master policy stops and your personal risk begins.

Some states have laws that regulate what an HOA’s master policy must cover. California doesn’t, so HOA master insurance coverage can vary significantly from one building to another.

In California, most HOAs insure only the part that the HOA maintains. Known as a “bare walls” policy, it covers the structure of the building and the rest of the common area but it doesn’t include the unit inside the “bare walls” drywall.

In that case, a unit owner’s HO-6 would need to cover cabinetry and appliances and light fixtures and flooring—all the things that come with the unit when you buy or sell it.

However, some HOAs have more extensive coverage, called “walls-in” coverage, that insures the units as well as the common area. (Most buildings with “walls-in” coverage are older buildings required by their CC&Rs to provide such coverage.) If your building has walls-in coverage, you can save money on your HO-6 because, other than the deductible on the HOA master policy, you already have coverage for the unit improvements for insurable events.

Your HOA’s certificate of insurance for its master policy will specify the type of coverage and deductibles. With that in hand, your insurance agent will be able to structure your HO-6 policy.

This information is intended as a brief introduction to the issues involved with condominium insurance. Please consult with an insurance agent or attorney or both for further information.

No matter where you are, you may find useful information here. Please be aware, though, that condominium laws vary greatly by state and some information may not apply to your region.

Some advice is specific to Los Angeles, while other information applies more generally to California. Overcoming the unique bureaucracy of LA and the Golden State is likely to be a recurring theme.

Note that California’s terminology is a bit different than in other states. In most states, the word “condominium” refers to the entire property, and the individual owner’s interest is a “condominium unit.” In California, under the Davis-Stirling Act, the entire property is called the “Condominium Project” while the word “condominium” refers to the unit owner’s interest in the Condominium Project.

CondoWonk is an advocate for policies that support condominium living, particularly in California.

Conversely, CondoWonk will call out policies that disadvantage condominium owners, particularly when compared to single family home ownership.

CondoWonk views the proper maintenance of aging condominium buildings as an affordable housing issue requiring public policy solutions. Most condominiums in California predate 1990 and are now 30, 40 or 50 years old. CondoWonk suggests and supports legislative changes to give HOAs the tools they need to evaluate their buildings’ needs and to fund needed repairs.

CondoWonk invites input from organizations and individuals with similar goals.

Have a question that wasn’t answered here? Or perhaps a topic you’d love to see us cover in a future article?

Scroll to Top